
Del 539
Econometrics of Financial High-Frequency Data
Häftad, Engelska, 2013
2 509 kr
Beställningsvara. Skickas inom 10-15 vardagar. Fri frakt för medlemmar vid köp för minst 249 kr.
Finns i fler format (1)
The availability of financial data recorded on high-frequency level has inspired a research area which over the last decade emerged to a major area in econometrics and statistics. The growing popularity of high-frequency econometrics is driven by technological progress in trading systems and an increasing importance of intraday trading, liquidity risk, optimal order placement as well as high-frequency volatility. This book provides a state-of-the art overview on the major approaches in high-frequency econometrics, including univariate and multivariate autoregressive conditional mean approaches for different types of high-frequency variables, intensity-based approaches for financial point processes and dynamic factor models. It discusses implementation details, provides insights into properties of high-frequency data as well as institutional settings and presents applications to volatility and liquidity estimation, order book modelling and market microstructure analysis.
Produktinformation
- Utgivningsdatum2013-11-29
- Mått155 x 235 x 21 mm
- Vikt587 g
- FormatHäftad
- SpråkEngelska
- Antal sidor374
- Upplaga2012
- FörlagSpringer-Verlag Berlin and Heidelberg GmbH & Co. KG
- ISBN9783642427725
Tillhör följande kategorier
Hoppa över listan
Mer från samma författare
Applied Quantitative Finance
Wolfgang Karl Härdle, Nikolaus Hautsch, Ludger Overbeck
Inbunden, 2008
1 359 kr
Hoppa över listan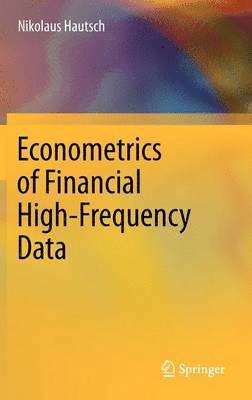
Du kanske också är intresserad av
Applied Quantitative Finance
Wolfgang Karl Härdle, Nikolaus Hautsch, Ludger Overbeck
Inbunden, 2008
1 359 kr
Del 539
- Nyhet
Del 3
- Nyhet
Del 11
- Nyhet
Del 6
Del 1
- Nyhet
Del 4
Del 3
Del 2